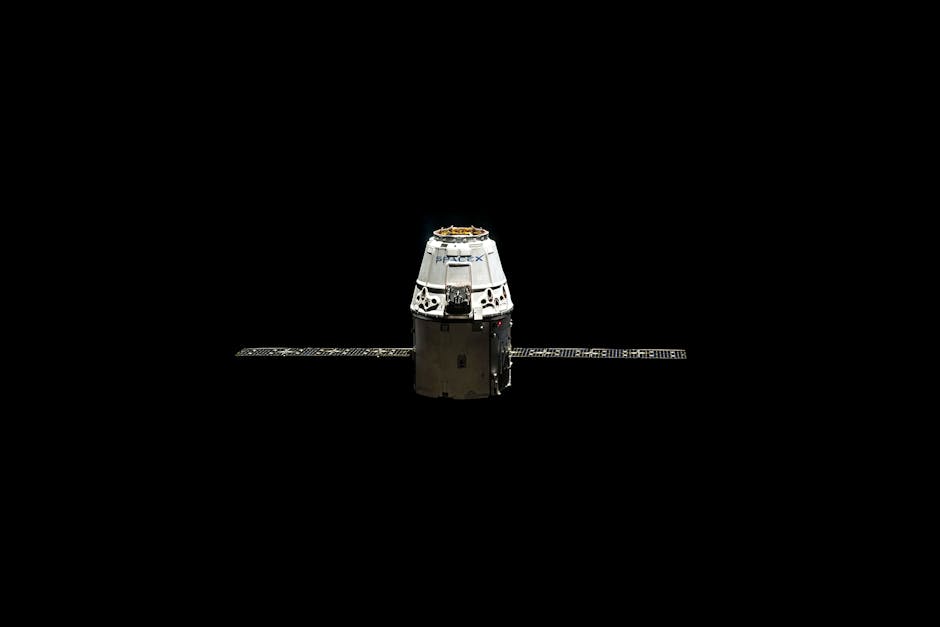
Valor Equity Partners, one of SpaceX's longest-standing private investors, is distributing SpaceX shares directly to its limited partners rather than converting its position to cash, according to TechCrunch. The move means investors in Valor's funds will receive equity in the rocket and satellite company itself, rather than a conventional cash payout.
To understand why this is notable, it helps to understand what it normally means when a private equity or venture fund reaches the end of its life cycle. Funds have a finite timeline, typically around ten years, at the end of which managers are expected to return capital to the institutional investors — pension funds, endowments, family offices — who committed money at the outset. The clean version of this is a cash distribution, which requires selling the underlying assets. The complication Valor faces, along with a growing number of funds holding late-stage private technology companies, is that its most valuable asset has not gone public and shows little urgency to do so.
SpaceX is one of the most valuable private companies in the world. Its valuation has climbed steadily through successive private funding rounds, and its business now spans orbital launch services, the Starlink satellite internet constellation, and ambitions toward Mars that attract a level of cultural attention no purely commercial aerospace company has managed before. Elon Musk has shown little inclination to take the company public in the near term, and there are credible strategic reasons for that: staying private keeps the company insulated from quarterly earnings pressure and from shareholders who might resist the kind of long-horizon, capital-intensive bets that define SpaceX's roadmap.
That creates a structural problem for early investors. Valor has been with SpaceX for many years, and its position is almost certainly worth multiples of what it originally paid. But an asset is only worth what you can actually realize from it, and without a public market or a willing buyer at scale, Valor cannot easily turn that paper gain into cash. The in-kind distribution — handing the shares themselves to LPs rather than cash — is one of the few tools available. It transfers the liquidity problem from the fund manager to the individual limited partners, who then have to decide what to do with private company stock they may or may not be equipped to hold.
This is not an isolated maneuver. The prolonged suppression of technology IPOs over the past few years has created a quiet crisis in the venture and growth equity world. Funds that invested in companies expected to list by now are sitting on positions they cannot easily exit. Some have sold stakes on secondary markets, accepting discounts to theoretical valuations. Others have sought fund extensions. The in-kind distribution approach, while less common, has a certain logic: it lets managers close out their obligations while allowing LPs who genuinely want long-term SpaceX exposure to keep the position, and allowing those who need liquidity to find buyers on their own terms in the secondary market.
The consequences of Valor's move ripple in a few directions. For the LPs receiving shares, the immediate question is practical: holding private company equity requires infrastructure that not every institutional investor has, and some may face internal rules that restrict them from holding illiquid assets beyond a certain threshold. Endowments with flexible mandates may welcome the shares; others may be motivated sellers, which could modestly increase the supply of SpaceX stock available on secondary markets without affecting the company's cap table in any direct way. For Valor, the distribution likely signals the wind-down of at least one of its older fund vehicles, a routine lifecycle event made unusual only by the fame of the underlying asset.
For SpaceX itself, the transaction is essentially administrative. The company does not receive new capital and does not participate in the transfer. What it does receive, in an indirect sense, is a reminder of the leverage that comes with staying private. Every time an early investor is forced to navigate around the absence of a public exit, it reinforces the dynamic Musk has cultivated: SpaceX sets the terms, and the capital markets adapt.
The thing to watch going forward is whether this transaction clears the path for Valor to raise a new fund, and how secondary-market pricing for SpaceX equity responds to any increase in supply from LPs looking to convert their shares. More broadly, SpaceX's trajectory toward its next funding round or any eventual public offering will determine how long other investors in similar positions can afford to wait. If Valor's move prompts other long-tenured SpaceX backers to consider similar distributions, it could gradually shift who holds the company's equity and what expectations those new holders bring with them.